IRS Releases Adjusted Contribution Limits for FSAs and Commuter Accounts
IRS Releases Adjusted Contribution Limits for FSAs and Commuter Accounts
On November 5th, the IRS released the 2027 maximum contribution limits for Flexible Spending Arrangements (FSA), commuter accounts, and adoption assistance. Rev. Proc. 2026-35 provides the inflation-adjusted items for 2027 for various code provisions.
For taxable years beginning in 2027, the annual contribution limit for health FSAs has increased from $3,400 in 2026 to $3,500. Additionally, the maximum carryover amount has also increased from $680 in 2026 to $700. The permissibility of carrying over unused FSA funds is dependent on the language of the cafeteria plan.
The maximum contribution amount for dependent care assistance plans will remain $7,500 in 2027. Employers increasing the amount employees can contribute to their dependent care assistance plan should be mindful of the nondiscrimination testing implications under IRC Section 129.
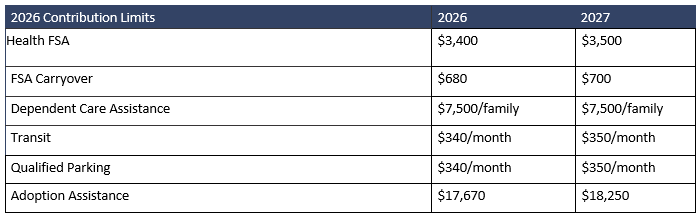
Finally, for taxable years beginning in 2027, the monthly limitation for transportation fringe benefits (e.g., commuter highway vehicle, transit pass, and qualified parking) increased from $340 in 2026 to $350. Adoption assistance benefit limits increased from $17,670 in 2026 to $18,250. The amount of the credit that may be refundable in 2027 is $5,280.